How to Start a Fast Food Franchise: 8 Smart Tips
Fast food franchises are dime a dozen around every corner, but the financing options available for them aren’t. Here’s what you need to do to have your cake and eat it—uh, sell it.
Fast food franchises are dime a dozen around every corner, but the financing options available for them aren’t. Here’s what you need to do to have your cake and eat it—uh, sell it.
Starting a fast food franchise can be your assured ticket to entrepreneurial success, but only if you approach it with the right strategy and sufficient capital.
The franchise industry generates over $800 billion annually in the US, with fast food representing a significant chunk of that pie.
Whether you’re eyeing a McDonald’s, Subway, or an emerging brand like Raising Cane’s, here are some smart tips to help you navigate the exciting (and financially demanding) world of franchising, and start your own fast food or QSR franchise.
Don’t let the advertised franchise fee fool you. A typical fast food franchise requires total investment ranging from $150,000 to $2.5 million, depending on the brand and location.
Here’s what you’re really looking at:
Take McDonald’s, for example. While their franchise fee is $45,000, the total investment ranges from $1.3 million to $2.3 million. Subway’s franchise fee is lower at $15,000, but total costs still run $116,000 to $263,000.
Smart tip: Factor in 6-12 months of operating expenses as working capital. Many new franchisees underestimate this and find themselves cash-strapped before they hit profitability.
Most franchisees need financing to get started, and the good news is that lenders often view established franchises as lower-risk investments compared to independent restaurants.
Your financing toolkit includes:
Many franchisors have relationships with preferred lenders who understand their business model. Subway, for instance, has partnerships with various lenders offering streamlined approval processes for qualified candidates.
Did you know there’s a dozen different types of loans available for small businesses?
The three rules of fast food success? Location, location, location. A study by the National Restaurant Association found that location accounts for up to 60% of a restaurant’s success.
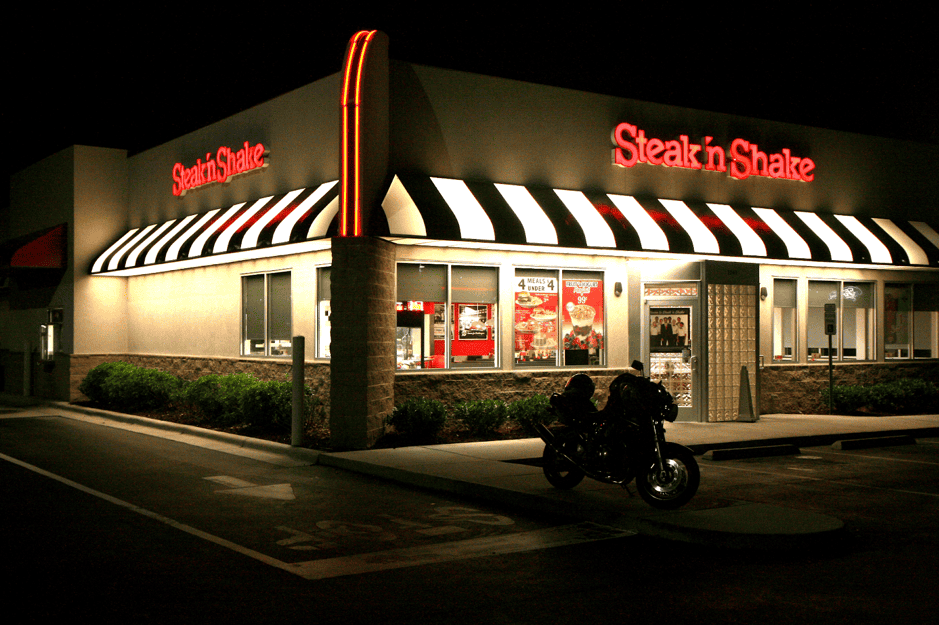
Image source: Wikimedia Commons
Look for these golden criteria:
Consider the success of Chick-fil-A locations near shopping centers and college campuses. They’ve mastered the art of demographic targeting. Their average unit volume exceeds $4 million annually, partly due to strategic location selection.
The FDD is your franchise bible—all 200+ pages of it. This legally required document reveals everything from the franchisor’s financial health to average franchisee earnings.
Pay special attention to:
Don’t skip the franchise agreement buried in the FDD. This contract governs your relationship with the franchisor for the next 10-20 years. Consider having a franchise attorney review it—it’s worth the investment.
Understanding when you’ll become profitable is crucial for cash flow planning. Most fast food franchises break even within 12-24 months, but this varies significantly by brand and location. Here are some key metrics to track:
Let’s say you’re opening a pizza franchise with an average ticket of $15. If your break-even point is $25,000 monthly, you need roughly 1,667 transactions per month, or about 56 per day. Factor in seasonal variations and local economic conditions.
The restaurant industry has a notoriously high turnover rate—around 75% annually. Having strong management in place from day one is essential. Your core team should include:
Many successful franchisees hire their management team 2-4 weeks before opening to allow for proper training. Some franchisors, like Jimmy John’s, provide extensive management training programs to help you build this team.
Whatever you do, choose your managers very, very carefully. I can’t emphasize this enough.
Don’t expect to hit full sales volume on day one. Most fast food franchises experience a gradual ramp-up period of 3-6 months as they build their customer base and refine operations.
Here’s a typical ramp-up pattern you can expect:
This is why adequate working capital is crucial. You’ll need to cover operating expenses, loan payments, and franchise fees even while sales are building. Many franchisees secure a working capital line of credit to smooth out cash flow during this period.
Need to infuse more capital into your business? Refused by multiple lenders?
Don’t sweat it. We can help.
Your financial commitments don’t end after the initial investment. Ongoing costs typically include:
For example, if you’re generating $50,000 monthly in sales with a 6% royalty fee, you’ll pay $3,000 monthly to the franchisor. Add a 3% marketing fee ($1,500), and you’re looking at $4,500 in franchise-related fees alone.
Starting a fast food franchise is both an exciting opportunity and a significant financial commitment. Success depends on thorough preparation, adequate financing, and realistic expectations about the challenges ahead.
The key is having your financing strategy locked down before you fall in love with a particular opportunity. Whether you need equipment financing for that $200,000 kitchen package or a comprehensive loan package covering everything from build-out to working capital, the right financial partner can make all the difference.
Remember, the most successful franchisees are those who treat their venture as a serious business investment, not just a way to “be their own boss.” With proper planning, adequate capital, and dedication to the franchisor’s proven system, your fast food franchise can become a profitable cornerstone of your financial future.
Looking for financing options for your takeaway place, cafe, or diner?
We have a specialized team to help you secure the capital needed to launch a successful restaurant business or franchise.
Contact us today to discuss your specific needs and explore our comprehensive lending solutions!
 https://goqualifi.com/wp-content/uploads/2026/10/3ef68a3ad3a4e493aaba4d7c7ae6a911.jpg
342
342
faras@brandmaximise.com
https://goqualifi.com/wp-content/uploads/2024/01/qualifi-new-logo-300x106.jpg
faras@brandmaximise.com2026-10-22 10:00:002026-10-21 23:31:07Should You Use a Line of Credit or Equipment Financing to Buy Equipment? Comparing Rates, Terms, and Monthly Payments
 https://goqualifi.com/wp-content/uploads/2026/09/c28f34e152f17d315201aa9b04fb665c.jpg
500
750
faras@brandmaximise.com
https://goqualifi.com/wp-content/uploads/2024/01/qualifi-new-logo-300x106.jpg
faras@brandmaximise.com2026-10-03 17:29:152026-10-03 17:29:16Does Applying for a Business Line of Credit Hurt Your Credit? Soft Pulls, Hard Pulls, and What Actually Shows Up
 https://goqualifi.com/wp-content/uploads/2026/09/28d312056197abb6c28c49748cce1bbe-1200x423-1.jpg
423
1200
faras@brandmaximise.com
https://goqualifi.com/wp-content/uploads/2024/01/qualifi-new-logo-300x106.jpg
faras@brandmaximise.com2026-09-25 15:01:472026-10-06 16:42:14My Bank Said No to a Line of Credit. What Should I Do in the Next 7 Days?
 https://goqualifi.com/wp-content/uploads/2026/09/18587fe8fd4d6d4d3185c96097dfb943-1.jpg
552
736
faras@brandmaximise.com
https://goqualifi.com/wp-content/uploads/2024/01/qualifi-new-logo-300x106.jpg
faras@brandmaximise.com2026-09-18 10:00:002026-09-18 01:08:22How Loan ‘Draws’ Work: Taking Money When You Need It Without Overborrowing
https://goqualifi.com/wp-content/uploads/2026/09/c28f34e152f17d315201aa9b04fb665c.jpg
500
750
faras@brandmaximise.com
https://goqualifi.com/wp-content/uploads/2024/01/qualifi-new-logo-300x106.jpg
faras@brandmaximise.com2026-09-18 08:00:002026-09-18 00:52:50Shorter Term or Lower Payment? The Trade-Off That Changes Your Total Cost
 https://goqualifi.com/wp-content/uploads/2026/09/ea16f862846dc63db3f466a30911bf7c.jpg
490
735
faras@brandmaximise.com
https://goqualifi.com/wp-content/uploads/2024/01/qualifi-new-logo-300x106.jpg
faras@brandmaximise.com2026-09-16 12:56:322026-09-16 12:56:38Bridge Loans Explained: How to Move Fast on Property Before Long-Term Financing Lands
 https://goqualifi.com/wp-content/uploads/2026/09/c451fc00b2abde8459d96285268b018d.jpg
667
1000
faras@brandmaximise.com
https://goqualifi.com/wp-content/uploads/2024/01/qualifi-new-logo-300x106.jpg
faras@brandmaximise.com2026-09-16 12:35:222026-09-16 12:35:28How to Fund an Add-On Acquisition to Grow Faster Than Your Competitors
 https://goqualifi.com/wp-content/uploads/2026/09/657dc1573177b0b57bab71d06db495d3.jpg
630
945
faras@brandmaximise.com
https://goqualifi.com/wp-content/uploads/2024/01/qualifi-new-logo-300x106.jpg
faras@brandmaximise.com2026-09-11 10:00:002026-09-11 05:00:13How to Trust a Lender Again After a Bad Experience
 https://goqualifi.com/wp-content/uploads/2026/09/b382cd642c50dc4a87a0b28bdb328bfd.jpg
675
1013
faras@brandmaximise.com
https://goqualifi.com/wp-content/uploads/2024/01/qualifi-new-logo-300x106.jpg
faras@brandmaximise.com2026-09-11 08:00:002026-09-11 04:49:47How to Tighten Your Payment Terms Without Losing Customers